Family finances work best when everyone understands the household’s priorities, limits, and shared responsibilities. Honest conversations can reduce confusion around spending and help families address problems before they grow. The process may feel uncomfortable at first, especially if money was rarely discussed in your home growing up. A few practical routines can make financial openness feel normal and help family members build trust over time.
Open Communication About Money
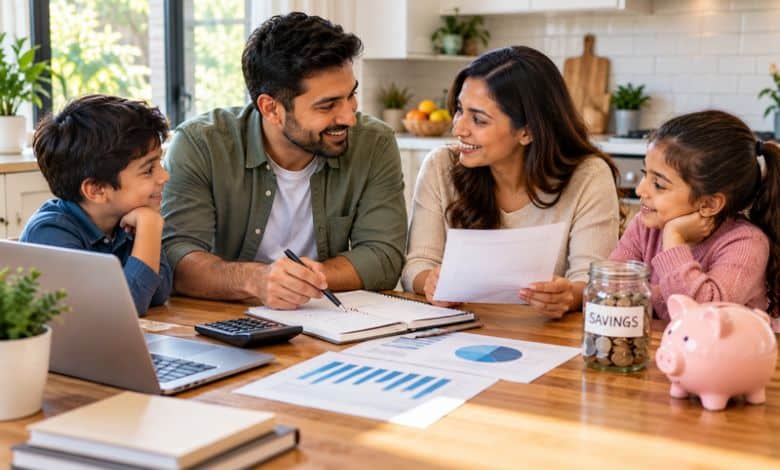
Set a regular time to discuss money when no one is rushed or upset. A 20-minute conversation after dinner once a month may be enough for routine updates. The goal is to share useful information without blame, including upcoming bills, changes in income, and progress toward family goals.
Guidance on starting a family wealth conversation recommends approaching the topic with clear intentions and including family members in age-appropriate ways. Keep the discussion focused with three questions:
- What expenses are coming up?
- Are we still on track for our main goal?
- Does anyone need help understanding a financial decision?
Listen carefully and avoid turning past mistakes into personal criticism. People are more likely to disclose concerns when they expect a calm response.
Creating a Transparent Family Budget
Build a budget that both adults in the household can view and understand. List monthly take-home income, fixed bills, flexible expenses, savings contributions, and debt payments. If income changes from month to month, use a conservative estimate and update the numbers when payments arrive.
Shared visibility matters when money is tight. Commentary from Alex Kleyner emphasizes transparency in financial services, including clear terms and fees. Families can apply the same principle at home by recording the full cost of commitments and discussing changes before agreeing to them.
A simple spreadsheet or budgeting app can work. Assign every expense a clear category, then schedule a 10-minute weekly check to catch duplicate charges, missed payments, or overspending early.
Teaching Kids About Financial Honesty
Give children small, practical opportunities to learn how money decisions work. A younger child can compare prices at the grocery store, while a teenager can plan a monthly clothing or entertainment budget. Use real numbers when appropriate, but don’t burden children with worries they can’t control.
Financial honesty also includes admitting mistakes. If a purchase causes the family to delay another plan, explain the adjustment in simple terms: “We spent more on the car repair this month, so we’ll wait two weeks before ordering the desk.”
Encourage children to tell you if they lose money, overspend, or misunderstand a purchase. Respond with a solution, such as reviewing a receipt or revising a savings plan. That reaction teaches them that financial problems should be discussed promptly instead of hidden, which is key to building financial security.
Choosing Reliable Financial Partners
Check any financial company carefully before sharing personal details or signing an agreement. Reliable providers explain their services in plain language and give you time to review costs. Ask for a written breakdown of fees, cancellation terms and expected timelines.
Use the same care when selecting a bank, financial adviser or debt relief provider. Watch for pressure to decide immediately, unclear promises or reluctance to provide documents. A trustworthy representative should answer questions directly and explain what happens if your circumstances change.
Couples may find financial strategies useful when discussing shared goals and responsibilities. Before meeting a provider, agree on the questions you’ll ask. Both partners should receive copies of contracts and know where account information is stored.
When to Seek Professional Guidance
Professional support can help when financial conversations repeatedly end in conflict, payments have become unmanageable, or the family faces a major change such as job loss, divorce, or caregiving costs. The right professional depends on the problem. A qualified financial counselor may help organize debt and spending, while a tax or legal professional can address specialized questions within their field.
Before an appointment, gather recent statements, bills, income records, and relevant agreements. Write down your top three concerns so the meeting stays focused. Ask how the professional is paid, which services are included, and what results are realistic.
Trust grows when family members can see the same figures and understand the next decision. Keeping one shared budget file current gives everyone a dependable place to start the next conversation.